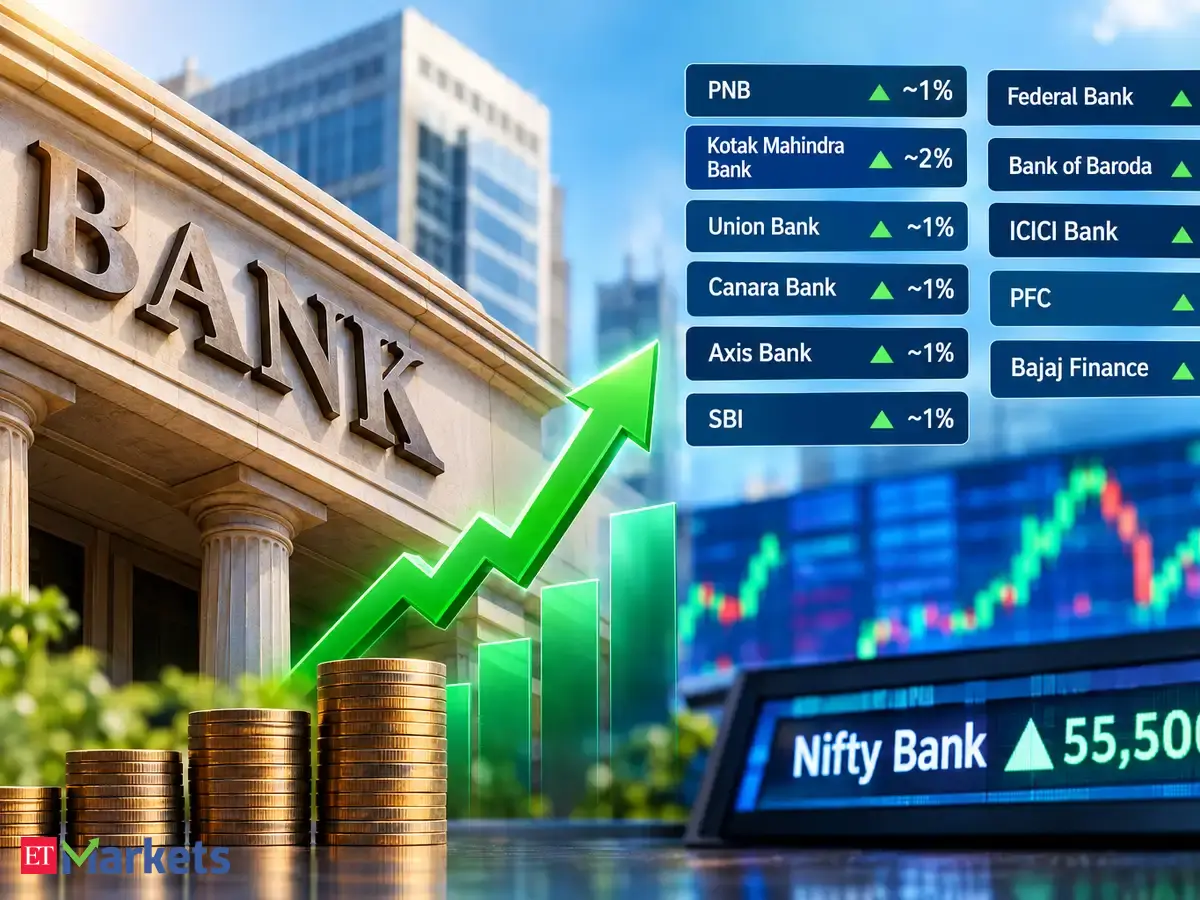
Bank stocks gained up to 2% on Wednesday after RBI Governor Sanjay Malhotra announced the MPC’s decision to hike interest rates for the first time in four years, helping the Nifty Bank index gain even as the broader market slipped into the red.
The Nifty Bank index gained more than 147 points to 55,276 on Wednesday morning after the MPC meeting outcome.
The Nifty 50, meanwhile, remained in the red, falling around 100 points to trade below 22,680, as of around 10:30 am.
Kotak Mahindra Bank shares rose 2%, while Union Bank , Canara Bank , Punjab National Bank ( PNB ), Axis Bank and SBI shares gained around 1% each.
Federal Bank , Bank of Baroda and ICICI Bank shares were trading in the green with marginal gains. Nifty Financial Services also moved into the green, with PFC, Bajaj Finance and others gaining up to 2%.
RBI Governor Sanjay Malhotra announced that the Monetary Policy Committee (MPC), after a detailed assessment of evolving macroeconomic and financial conditions, developments and the outlook, unanimously voted to increase the policy repo rate by 25 basis points to 5.50%. The standing deposit facility (SDF) rate now stands at 5.25%, while the marginal standing facility (MSF) rate and bank rate have been adjusted to 5.75%.
"The MPC noted that the global context, on account of geopolitical developments, remains challenging. Nonetheless, the Indian economy has been strong, and the economic momentum remains broad based.
Moreover, the economy is expected to remain resilient,” Malhotra said.
Despite fears, RBI increased its GDP projections, while striking a cautious note on inflationary pressures. Malhotra however dismissed hopes for near-term rate cuts as RBI changed its stance to ‘calibrated tightening’.
The 25 basis point rate hike was already priced in by the market, according to analysts. "Banks will benefit from the rate hike since rising floating rates will improve their margins," according to VK Vijayakumar, Chief Investment Strategist at Geojit Investments.
All eyes will now be on Q2 earnings for the banking space with focus remaining on margins which appears to be the only pain point at the moment, while growth holds firm and asset quality continues to remain resilient, said Dnyanada Vaidya, Research Analyst - BFSI, Axis Direct. Similar trends are visible in the provisional numbers reported by banks. Credit growth has remained strong and is expected to be broad-based. Deposit growth which was hovering between 11-12% over the last few quarters has picked-up meaningfully supported by strong FCNR(B) inflows.
However, near-term margins will continue to see pressure due to excess liquidity and lower-spread lending, the analyst from Axis Direct noted. “Outlook for NIMs turns constructive for H2, with rate hikes reflecting in EBLR-linked portfolios of banks. We believe private banks, especially larger private banks would be bigger beneficiaries. Asset Quality remains in a sweet spot, with no challenges visible from the prolonged West Asia conflict,” he added.
The next few months will be particularly important because the direction of crude prices, inflation and the rupee will determine whether today’s move is a one-off adjustment or the beginning of a broader normalisation of monetary policy, said Vijay Kuppa, CEO, InCred Money.