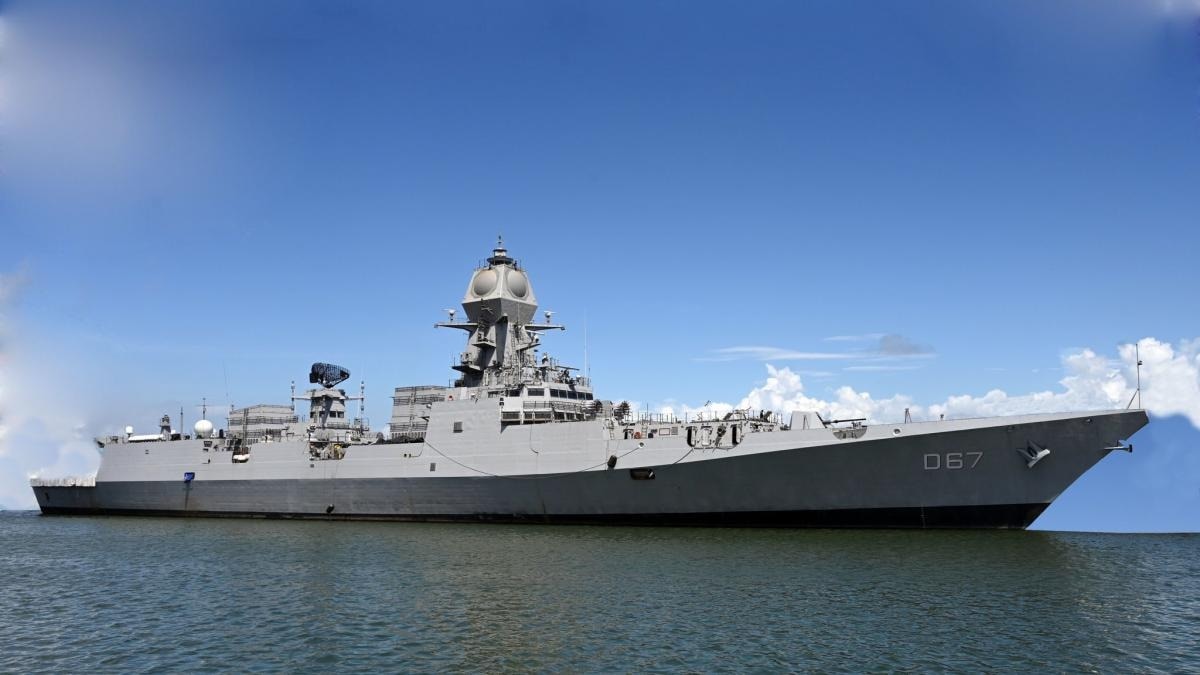
Garden Reach Shipbuilders & Engineers Ltd (GRSE) has received at least four 'Buy' calls, one 'Hold' and one 'Sell' recommendation following its September quarter results. The highest target on the defence PSU stock is from Choice Institutional Equities at Rs 3,500, while the lowest is from Goldman Sachs at Rs 1,735 per share.
Analysts recommending 'Buy' on the stock said Q2 remained subdued, but operating margins improved sequentially and progress across key programmes remained encouraging.
"We expect H2FY27 revenue momentum to improve, supported by the execution and delivery of the remaining ASW-SWC vessels, progress on the P-17 Alpha programme and continued construction across the NGOPV, research vessel and German MPV projects. Progression of these programmes towards equipment integration and outfitting stages is expected to support a stronger execution run-rate in H2FY27," Choice Institutional Equities said.
The brokerage said GRSE's order book provides strong medium-term revenue visibility.
As of June 2026, GRSE's order book stood at Rs 13,596 crore, implying 1.9 times FY26 revenue. Further strengthening its execution pipeline, the company signed a Rs 32,000 crore contract for five Next-Generation Corvettes in November 2026.
Including this contract, the pro forma order book increases to Rs 45,600 crore.
Elara Securities said Garden Reach reported subdued sales growth, likely due to slower execution. However, margins surprised positively, likely led by the execution mix, it said. The brokerage expects revenue generation from the Next-Generation Corvettes (NGC) order to commence in late FY29.
"However, we expect growth momentum to peak in FY27, due to the bell curve execution cycle. Thereafter, a mix of smaller ship orders and spares may sustain sales until NGC execution commences. We revise to Reduce (from Sell) due to receipt of NGC order with a target of Rs 2,230 as we roll forward," Elara said.
The stock has underperformed the Nifty by 30 per cent over the past six months.
Antique said GRSE's Q2 performance was below its expectations, with revenue and PAT missing estimates by 14.8 per cent and 16.6 per cent, respectively. It also noted a 139-basis-point year-on-year (YoY) expansion in Ebitda margins, led by lower subcontracting and project-related expenses.
"The key positive is the recent signing of the INR 320 bn Next Generation Corvette (NGC) contract, which lifts the order book to an estimated INR 420-440 bn, or ~5.5x TTM revenues. However, the early-stage nature of the NGC programme and slower-than-expected finalisation of other orders are likely to weigh on near-term revenue recognition. Accordingly, we have cut our earnings estimates. We maintain BUY with a revised target price of Rs 2,869 (earlier Rs 2,990)," it said.
Looking ahead, the execution of P-17 Alpha frigates, Next-Generation Corvettes, NGOPV and commercial shipbuilding programmes is expected to support sustained revenue growth over FY28-FY29, Choice said.