For a company planning an IPO, valuation helps inform the price at which its shares are offered to investors. For a given fundraising target, the issue price affects how many new shares must be issued and the resulting ownership dilution. A fresh issue raises capital for the company, while an offer for sale (OFS) allows existing shareholders to sell their shares and receive the proceeds.
Pricing also affects investor participation and post-listing performance. An issue priced too aggressively may face weaker demand or listing pressure, while a reasonably priced issue can improve its appeal. However, valuation alone does not guarantee strong subscription or listing gains.
India’s primary market highlights the importance of this decision. According to Grant Thornton Bharat, companies raised approximately ₹1.9 lakh crore through more than 360 IPOs in FY26, including ₹1.77 lakh crore through 109 mainboard IPOs. Despite this activity, listing gains and oversubscription declined, indicating more selective investor participation.
In H1 FY27, mainboard IPOs raised approximately ₹94,205 crore through 78 issues between April and September 2026, compared with ₹69,533 crore through 65 IPOs in the corresponding period a year earlier.
These figures highlight the scale of India’s IPO market, but fundraising activity alone does not determine an issue’s success. The key challenge is to set a price that reflects the company’s financial position, growth prospects and market conditions while remaining attractive to investors. This is where IPO valuation becomes essential.
IPO valuation is the process of estimating a company's financial worth before it offers shares to the public. Companies and their merchant bankers use financial information, business prospects and valuation methods to establish a reasonable valuation range.
A company’s valuation and its IPO pricing are related but distinct. Valuation estimates the company’s worth using financial performance, assets and liabilities, growth prospects and business risks. IPO pricing determines the price at which shares are offered to investors, taking into account valuation analysis, investor demand and market conditions.
The IPO issue price is also different from the listing price. The issue price is the price at which shares are allotted to IPO investors, while the listing price is the opening market price discovered on the stock exchange when trading begins. The listing price may be above, below or equal to the issue price.
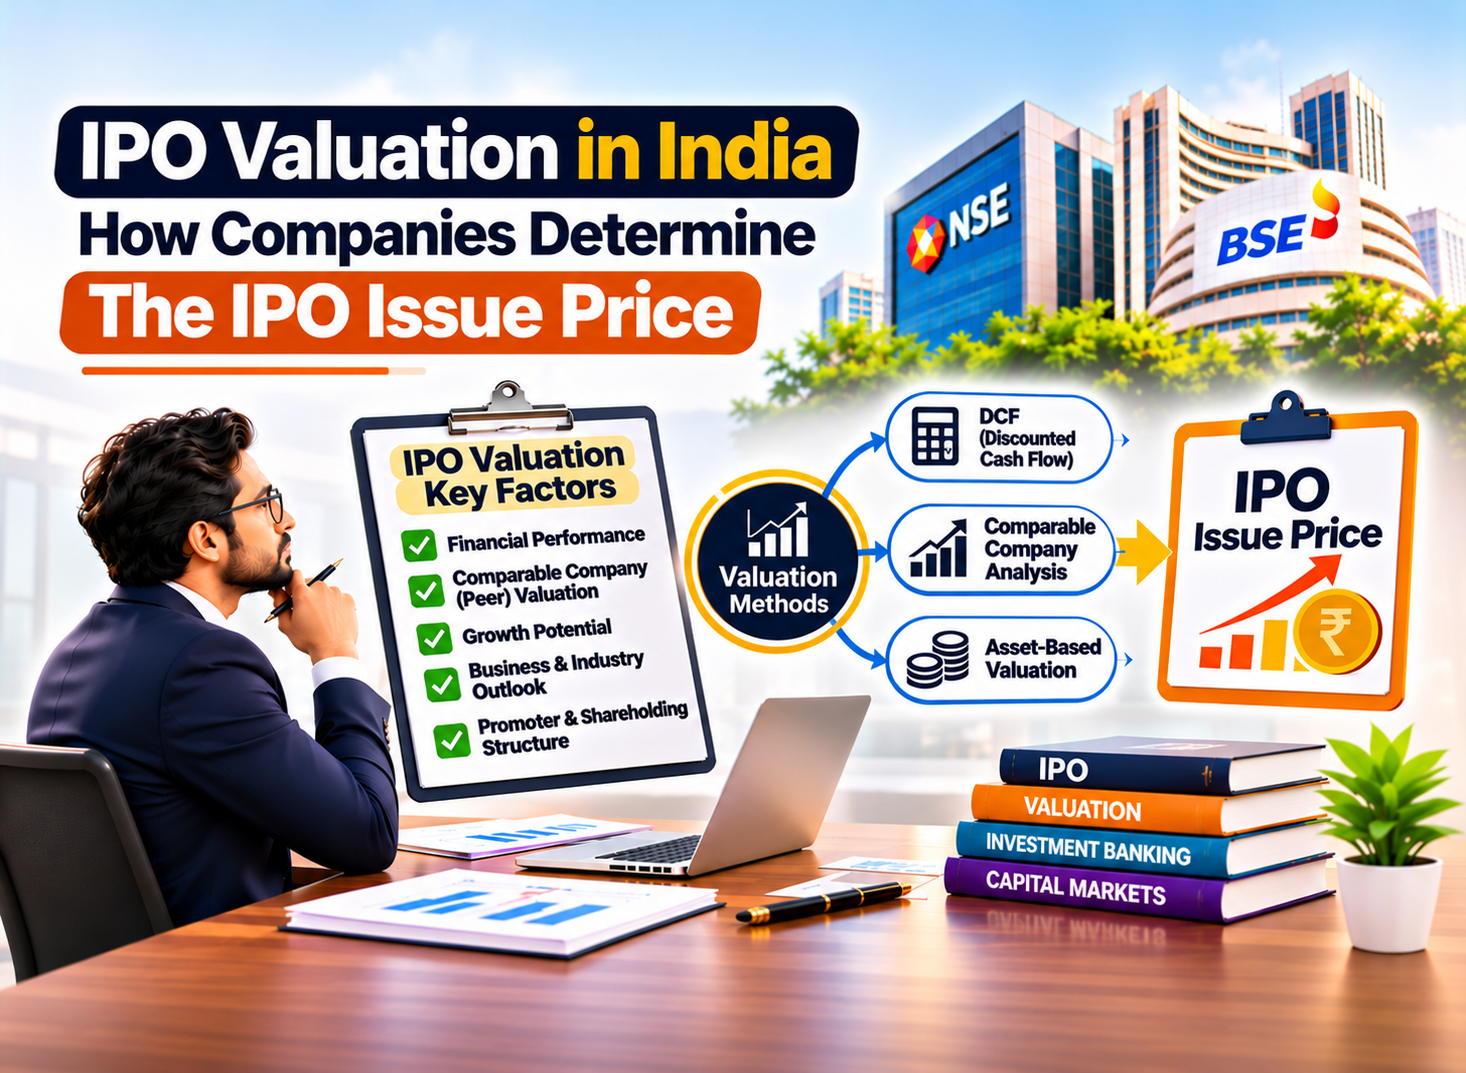
Before an IPO, companies assess their financial performance and compare their business with relevant listed peers. They may use methods such as discounted cash flow (DCF), price-to-earnings (P/E) analysis and comparable-company valuation to estimate a reasonable value.
In India, SEBI regulates public issues under applicable regulations that establish disclosure and pricing requirements but do not mean that SEBI certifies an IPO's valuation as fair.
IPO valuation depends on several financial and business factors. Companies should assess these areas well before filing their DRHP because weaknesses in financial performance or governance can affect the valuation investors are willing to accept.
Revenue growth: A consistent revenue-growth record helps demonstrate demand and business expansion. Companies should distinguish sustainable organic growth from acquisition-led growth and explain significant changes in revenue.
Profitability and margins: EBITDA, PAT, operating margins, return on equity (ROE) and return on capital employed (ROCE) help assess earnings quality and operating efficiency, but any decline in margins or inconsistent profits may weaken the valuation case.
Industry trends: Industry growth, competition, regulation and demand conditions influence the prospects of a business. Companies operating in different sectors may receive different valuation multiples because their growth opportunities, risks and capital requirements vary.
Competitive positioning: Market share, brand strength, pricing power, distribution reach and barriers to entry help determine whether a company can maintain its position against competitors. Customer concentration and dependence on a limited number of customers or suppliers can increase business risk.
Corporate governance: Reliable financial reporting, effective internal controls, transparent related-party transactions and sound board oversight support investor confidence. Material litigation, compliance weaknesses and unresolved governance concerns can complicate IPO due diligence.
Market conditions: Interest rates, liquidity, institutional investor appetite and recent IPO performance influence the valuation investors may accept. A company may need to reconsider its pricing expectations when market conditions weaken, even if its business performance remains stable.
Companies have different financial structures, growth prospects and business models. Merchant bankers therefore select valuation methods according to the company's characteristics and may use multiple approaches to cross-check the estimated value.
The discounted cash flow method estimates a company's value by calculating the present value of its expected future cash flows. It recognises that money received in the future is worth less than money received today.
The general formula is:
DCF = Sum [CFt / (1 + r)^t] + [TVn / (1 + r)^n]
Where:
CFₜ: Cash flow in period t.
r: Discount rate.
t: Time period.
n: Number of years in the explicit forecast period.
TVn: Terminal value at the end of year n.
The sum covers years 1 to n.
For a DCF valuation based on free cash flow to the firm, the discount rate is generally the weighted average cost of capital (WACC). The resulting estimate represents enterprise value.
A DCF model typically includes projected cash flows for an explicit forecast period and a terminal value representing cash flows beyond that period. Under the perpetual-growth method, terminal value is calculated as follows:
Terminal Value = FCFₙ × (1 + g) ÷ (r − g)
Where:
FCFₙ: Free cash flow in the final forecast year.
g: Assumed long-term growth rate.
r: Discount rate.
The discount rate must exceed the perpetual growth rate for this formula to produce a meaningful positive terminal value under the standard assumptions.
Best suited for: Businesses with reasonably predictable cash flows, such as mature manufacturers, infrastructure companies and utilities.
Limitation: DCF becomes less reliable when future cash flows are highly uncertain or depend on aggressive growth assumptions.
Illustration: Suppose a company forecasts free cash flow to the firm of ₹100 crore, ₹115 crore, ₹130 crore, ₹145 crore and ₹160 crore over five years. Assuming these cash flows occur at each year-end, a 12% discount rate and a 5% perpetual growth rate, the estimated enterprise value is approximately ₹1,818 crore, including the present value of the terminal value.
If the discount rate rises to 13% and the perpetual growth rate falls to 4%, the estimated enterprise value declines to approximately ₹1,448 crore.
This illustrates how sensitive DCF valuations can be to assumptions about future cash flows, discount rates and long-term growth.
Enterprise value is not the same as equity value. Analysts generally add cash and relevant non-operating assets and deduct debt and other applicable claims to estimate the value attributable to equity shareholders. Dividing equity value by the relevant share count gives an indicative value per share. The valuation date and treatment of fresh IPO proceeds must be consistent to avoid double-counting.
The P/E ratio compares a company's share price with its earnings per share. It helps investors assess how much they are paying for each rupee of earnings.
P/E Ratio = Market Price per Share ÷ Earnings per Share (EPS)
For valuation purposes, analysts may apply a justified P/E multiple, informed by comparable listed companies and the issuer's financial characteristics, to its earnings per share.
Best suited for: Companies with positive, reasonably stable earnings.
Limitation: P/E is not meaningful in the usual way for loss-making companies, and exceptional income or expenses can distort reported earnings.
Illustration: Assume annual PAT attributable to equity shareholders is ₹120 crore and the company has 10 crore equity shares outstanding after the IPO. For this simplified illustration, earnings per share calculated using the post-issue share count would be:
EPS = Rs 120 crore / 10 crore shares = Rs 12 per share
Applying an illustrative P/E multiple of 26 times:
Indicative Share Price = Rs 12 x 26 = Rs 312
The corresponding post-issue equity market capitalisation would be:
Equity Market Capitalisation = Rs 312 x 10 crore shares = Rs 3,120 crore
This simplified calculation should be distinguished from the historical EPS disclosed in the offer document. The earnings period and share-count basis should be stated clearly when comparing valuation multiples. The assumed multiple is illustrative, not a prescribed IPO multiple or a guaranteed market valuation.
Comparable-company analysis estimates a company's valuation by examining how similar listed businesses are valued in the market. Merchant bankers select peers based on factors such as business model, industry, size, growth, profitability and risk. They then compare relevant valuation multiples.
Common multiples include:
P/E: Equity value relative to earnings.
EV/EBITDA: Enterprise value relative to earnings before interest, taxes, depreciation and amortisation.
EV/Sales: Enterprise value relative to revenue.
Price-to-book (P/B): Equity market value relative to book equity.
Enterprise value (EV) is broadly calculated as:
EV = Equity Market Capitalisation + Debt − Cash and Cash Equivalents
Additional adjustments may be required for items such as minority interests and other non-operating assets or liabilities. A company with stronger growth prospects, margins or competitive advantages may justify a premium to selected peers. A smaller or riskier business may warrant a discount.
However, peer comparisons can be misleading when the selected companies have different financial characteristics or when the entire sector is trading at unusually high valuations. Relevant peer information and other prescribed disclosures are addressed in the applicable SEBI ICDR framework.
Asset-based valuation estimates a company's worth using the value of its assets and liabilities. An adjusted approach may restate assets such as land, buildings and investments to reflect their estimated current values.
A simplified formula for net asset value is:
Net Asset Value (NAV) = Total Assets − Total Liabilities
For equity valuation, assets and liabilities should be measured consistently, and material adjustments may be required.
Best suited for: Asset-heavy businesses, certain holding companies and investment businesses. Price-to-book (P/B) analysis is also relevant for many banks and non-banking financial companies (NBFCs).
Limitation: The method may not adequately capture the value of software, intellectual property, customer relationships, brands or other intangible assets, particularly in technology and service businesses.
These approaches are illustrative rather than exhaustive, and some overlap. For example, P/E analysis can form part of comparable-company analysis. Merchant bankers may use one or more approaches, including sector-specific methods, depending on the issuer’s financial profile, business model and valuation purpose.
Startups and established companies can require different valuation approaches because their financial histories, growth profiles and earnings visibility may differ.
|
Basis |
Startup IPO valuation |
Traditional company valuation |
|
Valuation focus |
Growth potential, scalability and market opportunity |
Earnings, cash flows and established business performance |
|
Profitability |
May involve limited profits or current losses |
May have a longer record of profitability, depending on the business |
|
Common metrics |
EV/Sales, P/S, projected cash flows and unit economics |
P/E, EV/EBITDA, DCF and sector-specific multiples |
|
Investor expectations |
Customer acquisition, expansion and a credible path to profitability |
Sustainable earnings, margins and cash generation |
|
Key risk |
Growth projections may not translate into sustainable profits. |
Established earnings may weaken because of competition or market changes. |
For startups, growth-based multiples must still be supported by credible revenue, sound unit economics and a realistic path to sustainable profitability.
IPO valuation in India combines financial analysis, regulatory disclosures and the public-issue pricing mechanism. The issuer and its lead merchant bankers assess the business and establish the proposed price range, while the applicable regulations govern the issue process and disclosures.
Book Running Lead Managers (BRLMs) coordinate important parts of the IPO process, including due diligence, valuation analysis, preparation of offer documents and management of the book-building process where applicable.
They assess the issuer's financial performance, business risks, projections and comparable listed companies. Their due diligence and disclosure responsibilities operate alongside those of the issuer and other parties responsible for information in the offer documents.
SEBI's ICDR Regulations, 2018, establish requirements for public issues, including pricing procedures and disclosures. The offer document's Basis for Issue Price section contains prescribed financial information and relevant valuation-related disclosures to help investors assess the proposed price. But, SEBI does not determine the company's fair value or guarantee that the issue price is appropriate. Investors must assess the disclosed information and associated risks themselves.
Before and during the IPO process, issuers and their merchant bankers may engage with institutional investors to understand their views on the company's business prospects, valuation and proposed issue price. Such feedback can inform pricing expectations, but it does not guarantee demand or establish an objectively correct valuation.
In a book-built IPO, the issuer determines a price band in consultation with the lead merchant banker, in accordance with applicable regulations. Investors submit bids within the permitted range, and the final issue price is determined through the book-building process.
Demand at different price levels helps the issuer and lead managers assess the price at which the issue can be completed, subject to the applicable rules and allocation requirements. The price band is therefore a mechanism for price discovery; it is not itself a guarantee of the company's fundamental value.
For a company preparing to go public, the valuation process generally involves six stages.
Step 1: Financial and Business Performance Assessment
The company reviews its restated financial statements, including revenue, profitability, cash flows, debt and contingent liabilities. Merchant bankers examine earnings quality, exceptional items, related-party transactions, capital expenditure requirements and future funding needs to understand the company's financial position.
Step 2: Industry and Peer Benchmarking
The company is compared with relevant listed businesses to assess differences in growth, profitability, operating efficiency, leverage and valuation, which helps management understand its competitive position.
Step 3: Selection of Valuation Methods
The valuation approach depends on the company's business model and financial profile. Merchant bankers may use multiple methods to cross-check the estimated valuation range.
Step 4: Valuation Review and Investor Feedback
Management and merchant bankers review the proposed valuation in light of the company's financial performance, peer benchmarks and market conditions. Investor discussions, where applicable, can help identify concerns about growth assumptions, profitability, governance or the proposed issue price. Management can use this feedback to reassess its expectations.
Step 5: IPO Price Band Determination
The issuer and its lead managers determine the price band by considering the valuation analysis, market conditions, capital-raising objectives and applicable regulatory requirements. Pricing must be considered alongside the proposed issue structure, including any fresh issue and offer for sale (OFS), with the prescribed disclosures made in the relevant offer documents.
Step 6: Final Issue Price and Listing Preparation
After bidding closes, the final issue price is determined through the applicable pricing mechanism. The issue then proceeds through allotment, share credit and listing formalities within the prescribed timelines.
Overall, IPO valuation is therefore a structured assessment rather than a decision to seek the highest possible price. A credible valuation must be supported by the company's financial performance, business prospects and disclosed assumptions.
Valuation multiples vary across sectors because businesses differ in growth prospects, profitability, capital requirements and risk. The following metrics are commonly used to compare companies within relevant industries.
Technology companies: EV/Sales may be useful for high-growth companies with limited or negative earnings. EV/EBITDA and P/E become more relevant as profitability improves. Revenue quality, recurring income, customer retention and the path to sustainable profits are important considerations.
Manufacturing companies: EV/EBITDA and P/E help assess operating performance and earnings. Order-book visibility, capacity utilisation, operating margins, working capital and ROCE can help explain differences between companies.
Financial services firms: Banks and NBFCs are commonly assessed using P/B and P/E alongside ROE. Asset quality, capital adequacy, loan growth, funding costs and credit risk are important valuation considerations. Insurance companies and asset managers may require additional sector-specific metrics.
Consumer businesses: P/E and EV/EBITDA may be used alongside indicators such as same-store sales growth, where applicable. Brand strength, distribution reach, repeat purchases, pricing power and profitability help establish competitive positioning.
Capital-intensive businesses: EV/EBITDA and cash-flow-based approaches can be useful for companies requiring substantial investment in plants, equipment or infrastructure. Capital expenditure, leverage, asset utilisation and future funding requirements are important.
Growth-stage companies: Revenue multiples and projected cash flows may provide useful context when current earnings are limited. Customer acquisition costs, retention, unit economics and the ability to achieve sustainable profitability help assess the credibility of growth expectations.
Market conditions: Interest rates, liquidity, investor demand and market sentiment can change the multiples investors are willing to pay. A multiple observed in one IPO or market cycle should not automatically be applied to another company.
Sector multiples are reference points, not fixed valuation rules. A defensible comparison requires relevant peers and an assessment of the reasons for differences in their financial performance and risk.
IPO valuation mistakes can result in unrealistic pricing expectations, difficult investor discussions or weak post-listing performance. Companies should avoid the following errors.
Overvaluation driven by market hype: Strong interest in a sector does not establish the value of an individual company. Valuation expectations should be supported by the issuer's own financial performance, business prospects and relevant benchmarks.
Unrealistic growth assumptions: Overestimating revenue growth, profit margins or market share can inflate a valuation. Projections should reflect historical performance, customer demand, operating capacity, funding needs and clearly stated assumptions.
Ignoring peer benchmarks: Comparing a company with businesses that have different operating models, growth rates or profitability can produce misleading results. Peer selection should reflect meaningful similarities and differences.
Using an unsuitable valuation method: A valuation metric that does not fit the business model may distort the estimated value. For example, P/E is not meaningful in the usual way for a loss-making company, while price-to-book can be particularly relevant for certain financial businesses.
Overlooking debt and cash-flow requirements: Reported profits do not necessarily mean a company has sufficient cash to meet its obligations. Borrowings, interest costs, working capital and capital expenditure must be considered when assessing financial flexibility and valuation.
Weak corporate governance and disclosures: Incomplete financial records, unclear related-party transactions, unresolved legal matters and weak internal controls can complicate IPO due diligence and undermine investor confidence. Companies should identify and address material issues before filing their offer documents.
Relying excessively on IPO demand: Oversubscription indicates demand at the offered price, but it does not independently prove that the valuation is justified by the company's fundamentals. Strong initial demand also does not guarantee listing gains or long-term share-price performance.
Aggressive pricing can increase the risk of post-listing downside if market expectations are not supported by business performance. However, a share price falling below the issue price does not, by itself, establish that the original valuation was incorrect.
Before launching an IPO, a company can use the following checklist to identify gaps in its financial preparation and valuation rationale.
Financial performance: Review audited financial statements, including revenue, expenses, assets, liabilities and cash flows. Identify exceptional items, contingent liabilities and related-party transactions that may affect the company’s reported financial position.
Revenue growth: Examine revenue trends across financial periods, identifying key growth drivers, customer concentration, repeat business and dependence on major contracts. Ensure that future projections are supported by documented business plans.
Profitability metrics: Assess gross profit margins, EBITDA, profit after tax (PAT), earnings per share (EPS) and return on capital employed (ROCE), where relevant. Review changes in margins and explain significant cost increases or declines in profitability.
Peer comparison: Compare the company with listed businesses operating in similar sectors and business models. Evaluate relevant valuation multiples, such as P/E, EV/EBITDA, or price-to-book value, while accounting for differences in growth, profitability and financial risk.
Debt and cash-flow position: Examine outstanding borrowings, interest costs, repayment schedules and working capital requirements. Assess whether operating cash flows are sufficient to support business operations and meet financial commitments.
Governance and compliance: Review board composition, internal controls, audit practices, related-party transactions, promoter interests, pending litigation and regulatory compliance. Ensure that material information is accurately disclosed in the offer documents.
Business risks: Identify significant risks arising from competition, suppliers, customers, regulations and operational dependencies. Assess their potential effect on business continuity, revenue and profitability.
Use of IPO proceeds: Define how funds raised through a fresh issue will be used, such as for capital expenditure, debt repayment or working capital. Ensure that the proposed allocation matches documented business requirements and is clearly disclosed.
Investor demand and market conditions: Evaluate institutional investor feedback, comparable IPO performance and prevailing market conditions during the IPO process. In a book-built issue, bidding demand helps determine the final issue price, but market interest does not independently establish the company’s fundamental value.
Completing these checks helps management prepare a more defensible valuation and identify issues that may require attention before the IPO process advances.
IPO valuation combines financial fundamentals, business prospects and market-based comparisons to estimate a company's worth. Methods such as DCF, P/E, comparable-company analysis and asset-based valuation provide different perspectives, while the book-building process helps determine the final issue price in a book-built IPO.
A credible valuation depends on realistic assumptions, relevant benchmarks, reliable financial information and transparent disclosures. Although these factors can support informed pricing decisions, they cannot guarantee subscription levels, listing gains or long-term share-price performance. For companies preparing to enter the public market, the priority should be a valuation that can be justified by the business and its financial prospects.
The INDIA IPO Publication is managed by an editorial team that includes highly experienced finance journalists, market researchers and professionals from the capital markets industry who strive to create high-quality content based on credible sources. Our editors write about IPOs, capital markets, corporate news, capital-raising strategies, regulations and other business matters to ensure our audience stays updated with the latest information. We conduct detailed research and fact-check all information before publishing any content to ensure credibility.
Next Reading
Strategic IPO Planning
Join hundreds of founders who scaled their vision with India's most trusted public listing advisory network.
Verify EligibilityQuick IPO Resources
Trending News